In the volatile world of Bitcoin treasury companies, market dips often present the most compelling, but scary, entry points for long-term investors. Today Metaplanet saw its mNAV fall below 1 for the first time since launching its Bitcoin treasury strategy in 2024. Closing at ¥482 with an mNAV multiple of 0.99x, the stock has declined 12% in a single session and more than 70% from its June highs. Yet, beneath that compression lies a signal: the rare convergence of strong fundamentals, disciplined execution, and asymmetric upside for those who believe in the power of compounding Bitcoin per share.
A Discounted Balance Sheet in a Bull Market
Metaplanet’s enterprise value has now slipped below its $3.5 billion Bitcoin reserve — 30,823 BTC accumulated at an average of $107,912 per coin. Despite the drawdown, the stock remains up 35% year-to-date, still outperforming the S&P 500 by a wide margin. Investors who treat it as a passive Bitcoin ETF miss the deeper signal: balance sheet integrity and leverage discipline. With debt covered 139 times by Bitcoin NAV and leverage under 1%, Metaplanet is preparing to launch phase 2 of their plan.
For active Bitcoin investors, this pricing anomaly has the hallmarks of arbitrage: equity trading at a discount to underlying BTC, with upside torque through accretive treasury mechanics.
Explosive Growth in Bitcoin per Share
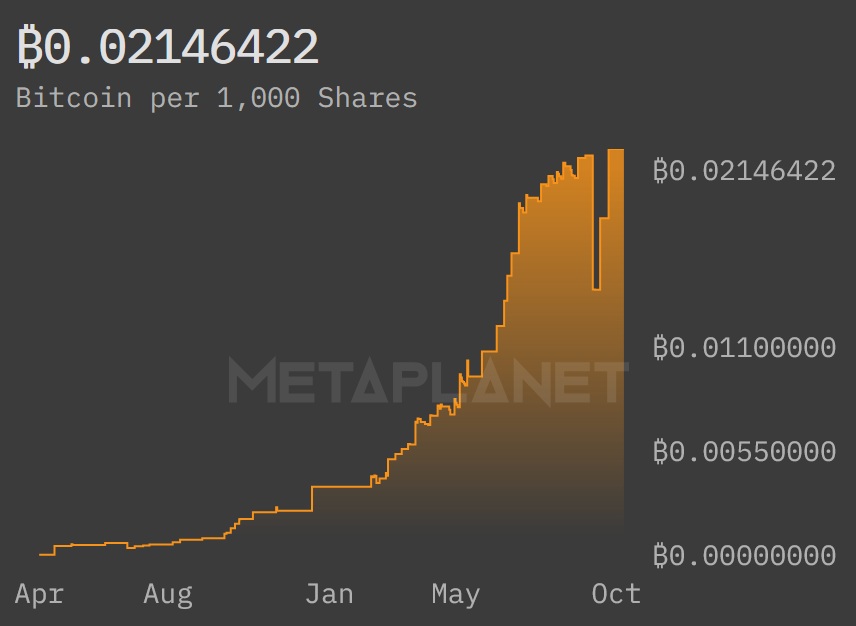
Metaplanet’s strategic core is Bitcoin per share — and that number tells the real story. When the company began its Bitcoin accumulation program just 18 months ago, each share represented only 46 satoshis. Today, that figure exceeds 2,146 sats, a 46.7x rise that places Metaplanet among the world’s top corporate accumulators. The company’s 30,823 BTC stack now ranks fourth globally, and over half of it — 17,473 BTC worth $2 billion — was added in just the last quarter.
On October 1, Metaplanet executed a single acquisition of 5,268 BTC for $615.67 million at $116,870 per coin, propelling its year-to-date BTC yield to nearly 500%. Its international offering earlier in the year generated a 10.5% return on capital, converting $1.211 billion into $1.338 billion worth of Bitcoin — a $126.9 million mark-to-market gain in months.
If Bitcoin reaches $1 million, the current BTC-per-share structure implies intrinsic value near $21.49 per share. Analysts model as much as 5x growth in Bitcoin per share within five years under the company’s planned leverage program — levels that could push fair value north of $100 at that Bitcoin price.
Phase II: Perpetual Preferreds and Dilution-Free Yield
Metaplanet’s newly unveiled “Phase II” plan introduces perpetual preferred shares — a novel capital instrument designed to fund additional Bitcoin accumulation without common stock dilution. Targeting 25% of NAV, roughly $940 million, the prefs could finance another 7,520 BTC at a $125,000 average price.
The innovation lies in structure: tapping Japan’s ¥7.5 trillion idle cash base with yield-bearing securities while keeping ordinary equity intact. Preferreds serve as a lever, not a release — converting balance-sheet strength into compounding Bitcoin exposure.
Alongside this sits a booming Bitcoin Income Generation unit, which reported record Q3 revenues of ¥2.44 billion ($16.5 million), up 115.7% quarter-over-quarter. The desk’s cash-secured put operations now fund preferred coupons directly, creating recurring Bitcoin yield without liquidating reserves.
Internally, Project NOVA — a classified 2026 initiative — is rumored to extend Metaplanet’s operating reach into Bitcoin exchange or yield platforms. Coupled with Bitcoin.jp and a NASDAQ listing pathway, the company’s roadmap points toward institutional distribution, enhanced liquidity, and new investor channels.
The long-term mandate remains explicit: reach 210,000 BTC by 2027 under the “555 Million Plan, scaling both operational leverage and Bitcoin per share.
Market Context: Mispricing in Motion
Market sentiment has yet to price Metaplanet’s earnings power. The company’s Q3 operating profit exceeded forecasts by 88%, while its debt-free balance sheet and capital discipline remain unmatched in the sector. The mNAV slide below 1.0x recalls historical dislocations like Amazon’s post-dot-com trough — temporary divergences between fundamentals and market mood.
At current levels, even modest yield recovery could reset valuation. At 1.07x mNAV, a 7% rise in Bitcoin or a 7% treasury yield recovery would return the stock to parity. With buybacks and warrant suspensions in effect, supply-side pressure is tightening, setting up the potential for short-covering volatility.
The Signal Take
In conclusion, Metaplanet’s sub-1x mNAV isn’t a red flag—it’s a gift. With Phase II unlocking dilution-free leverage, surging revenues, and a clear path to 5x+ BTC per share growth, this dip could mark the entry point for generational wealth. As CEO Simon Gerovich reminds us, “Execute relentlessly. Build revenue. Accumulate bitcoin.”
For Bitcoin Treasury believers, the future looks brighter than ever.