For a Bitcoin treasury company, success is measured in one metric: the growth of Bitcoin per share. When the market prices your equity below the value of the stack it represents, that discount isn’t a sentence—it’s a tool. Sub-1 mNAV is the moment to weaponize the capital structure and compound scarcity for the shareholders. The mandate is simple: convert temporary mispricing into permanent BTC/share accretion.
Turning the mNAV Discount into more BTC per share
During bullish periods, most Bitcoin treasuries did the opposite—they monetized optimism. When premiums were high, they leaned on at-the-market programs, private placements, and convertible notes to issue new equity above mNAV. It was rational at the time: the market was willing to pay more per share than the Bitcoin each share represented. That premium issuance expanded treasury reserves, grew total BTC, and, for a while, fed the narrative of “stacking through dilution.”
Now, with many treasuries trading below 1 mNAV, the market is forcing the mirror image of that strategy. Just as the premium was once monetized with issuance, the discount must now be monetized with buybacks.
When a Bitcoin treasury trades below 1 mNAV, each share is changing hands for less Bitcoin than it represents. That mispricing is an opportunity. Buying back stock below book value removes claims on the treasury at a discount, so every coin used to fund the buyback cancels more than one coin’s worth of claim.
The effect is immediate and lasting: Bitcoin per share increases.
The Math
Imagine a company holding 10,000 BTC with 100 million shares outstanding—100 sats per share. The market values the equity at 0.80× mNAV.
Management sells 100 BTC to repurchase stock in the open market. Because the shares are trading at a 20% discount, those 100 BTC buy back claims on 125 BTC worth of equity. Treasury Bitcoin drops to 9,900 BTC, but the share count contracts by the portion that represented 125 BTC. The result: more Bitcoin per share, permanently.
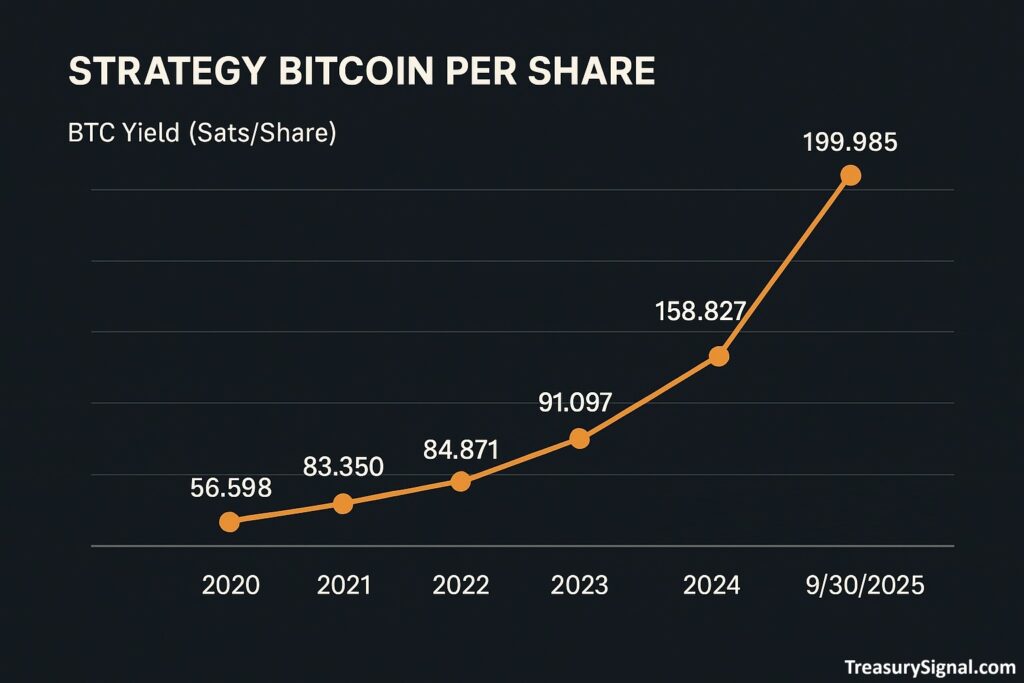
The entire point “never sell a single Bitcoin” is meaningless if BTC/share stagnates. Below 1 mNAV, the standard should shift from “never sell” to “never miss accretion.”
Funding the Buy
You don’t need to sell the whole stack to fix the mispricing. There are clean ways to fund sub-par repurchases while protecting the long-term position.
Direct BTC for buybacks:
The simplest move. Sell a small slice of coins, buy your own equity at a discount, and destroy those claims. Bitcoin on the balance sheet dips, but BTC per share climbs—the core objective.
BTC-backed credit:
Borrow against your Bitcoin through a conservative, term-secured facility. Use the cash to buy back discounted stock while preserving headline holdings. Keep maturities long and LTV low enough to ride through a bear market without forced sales.
Preferreds or perpetuals:
Issue non-voting, yield-bearing paper to fund buybacks. The float tightens, the denominator shrinks, and common holders see direct accretion without touching the treasury.
Below par, the cheapest Bitcoin on the planet is our own.
Controlling the Flow
Stocks don’t trade below book in isolation. Extended discounts feed on poor treasury management—endless ATM issuance, short pressure, and liquidity gaps. The fix isn’t talk; it’s control.
Shut down equity pipes when the premium compresses. Never issue at or below parity.
Keep a standing buyback authorization for sub-1 mNAV conditions, with pre-set limits and volume rules.
Show discipline to the market. Shorts close when the issuer becomes the bid.
Trading below 1 mNAV is no longer a reason to hide, it’s the time to make moves. It’s not ideology; it’s math. If management won’t buy back, someone else will buy the whole company.
Market Conditions and the Scarcity Loop
Falling rates make it easier to borrow against Bitcoin, widening the menu for buyback financing. At the same time, institutional money is flowing into long-duration, low-turnover holdings—both BTC itself and the equities backed by it.
Repurchasing below 1 mNAV in that environment does two things at once: increases BTC/share and tightens float into rising liquidity. It’s reflexive, and it rebuilds the premium.
The Signal Take
Trading below 1 mNAV isn’t failure, it’s an opportunity. Buy back when the market misprices, use credit and preferreds smartly and measure every action in BTC per share.