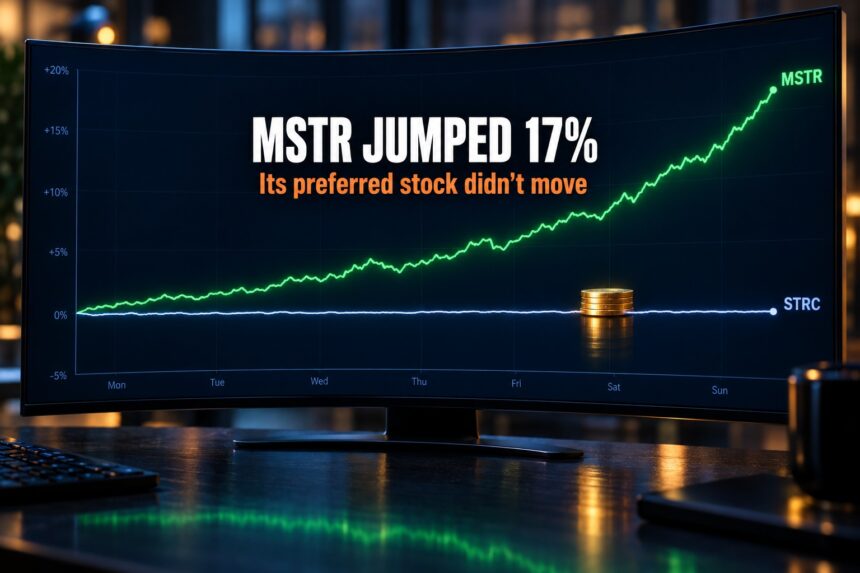
MSTR did not share its 17.56% gain with its preferred stock last week. While MSTR surged, the STRC preferred stock moved just -0.07%.
The divergence shows that digital credit trades on different rules than common stock.
STRC is Strategy’s preferred stock designed to trade near its $100 par value. It is a credit instrument, not an equity proxy.
By the Numbers
Here is how the assets performed during the week of September 8-13, 2026:
- 17.56%: the gain for MSTR.
- 4.40%: the rise in the IBIT bitcoin ETF.
- -0.07%: the return for the STRC preferred stock.
- $139.3 million: the cash Strategy spent buying back STRC.
Why STRC is priced like credit
How a preferred stock works:
- Fixed priority: Preferred stock sits ahead of common equity but behind debt.
- Stated par: The shares are issued with a $100 par value that anchors the price.
- Regular income: The board sets a dividend rate, currently 12.00% per annum, paid semi-monthly.
- No upside: Holders receive cash dividends but no share of the growing bitcoin stack.
For a worked example, look at Strategy’s actions during the week ending September 13, 2026. The company spent $139.3 million to buy back 1,420,467 shares of STRC.
It bought these shares at a discount to their $100 par value. This reduced the preferred claims ahead of the common stock.
Retiring shares below par also trims the dividend bill that sits ahead of common shareholders.
Three main forces drive the STRC price. First is the dividend rate, which the board maintains at 12.00% per annum. Second is trust in the company’s ability to pay. Third is broader interest rates. When rates rise, preferred prices fall.
Unlike a bitcoin proxy, the bitcoin preferred stock price responds to credit signals rather than token momentum. STRC has an adjustable dividend rate that the board reviews monthly, paying it out semi-monthly in cash to keep the price near par.
We previously analyzed how this buyback strategy retires preferred shares to protect common holders.
BitStrategy pointed out the striking divergence on X, noting that the price action tests whether bitcoin drives the preferred stock.
BitStrategy (@BitStrategy21)
If bitcoin and MSTR were the primary drivers, STRC should have rallied. Instead, the preferred stock sat flat, suggesting that credit metrics matter more than bitcoin momentum.
This divergence affects how investors calculate the company’s valuation. When analyzing the premium of the stock over its holdings, known as mnav, the preferred debt must be factored in.
Watch
- Another week of buybacks: whether Strategy continues to spend cash to retire STRC.
- The dividend rate decision: whether the board maintains the 12.00% rate or raises it to attract buyers.
- STRC back at its $100 face value: whether the preferred stock can finally close the gap to par.
Signal Take
STRC is a credit instrument, not a bitcoin proxy. Its price is bound by interest rates and credit trust, not bitcoin momentum. Common equity holders capture the upside of the treasury, while preferred holders only receive fixed income.
What would change our mind: a month of STRC tracking bitcoin’s weekly moves instead of its own dividend rate, or a rate decision that moves the price nowhere. Either would mean the market is pricing it on the treasury, not on the payout.